Roth or 401k Calculator: 7 Powerful Tips for Retirement
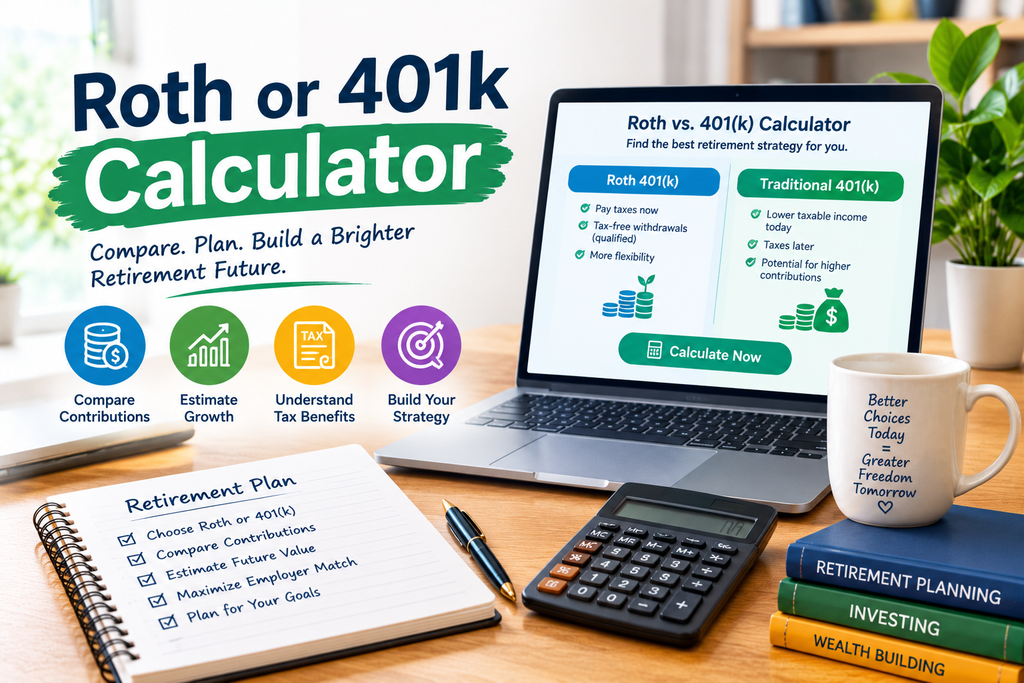
Choosing between a Roth 401(k) and a traditional 401(k) can affect how you pay taxes today and how much of your retirement money you may keep after taxes. A Roth or 401k calculator can help you compare the two approaches using your age, contributions, expected tax rates, retirement timeline, and potential investment growth.
The important thing is not to treat a calculator result as a guarantee. A calculator is a planning tool that uses assumptions. Your actual outcome will depend on contributions, investment performance, taxes, fees, employer contributions, and future tax rules.
The IRS explains that traditional 401(k) contributions are generally made on a pre-tax basis, while designated Roth contributions are included in taxable income when contributed. Qualified Roth distributions can generally be tax-free under the applicable rules.
What Is a Roth or 401k Calculator?
A Roth or 401k calculator is a retirement-planning tool that estimates how a traditional 401(k) and Roth 401(k) may compare under different assumptions.
The calculator typically asks for information such as:
- Current age
- Current retirement savings
- Annual income
- Annual contribution
- Expected retirement age
- Current tax rate
- Expected retirement tax rate
- Expected investment return
- Employer contribution or match
- Whether traditional 401(k) tax savings are also invested
John Hancock’s calculator, for example, allows users to compare traditional and Roth 401(k) contributions by entering assumptions about savings, taxes, retirement age, and expected returns.
The goal is not to predict the future perfectly. Instead, the calculator helps you understand how different assumptions can change the estimated result.
That makes it especially useful when you’re deciding whether paying taxes now or later may fit better with your retirement strategy.
Roth or 401k Calculator: How Does It Work?
The basic difference comes down to when you pay income tax.
With a traditional 401(k), eligible contributions are generally made before federal income tax is applied to those wages. Taxes are generally paid when money is distributed from the account.
With a Roth 401(k), designated Roth contributions are made with after-tax income. The contributions are included in taxable income when made, while qualified distributions can generally be tax-free.
A simple comparison looks like this:
| Feature | Traditional 401(k) | Roth 401(k) |
|---|---|---|
| Contribution tax treatment | Generally pre-tax | After-tax |
| Tax benefit | Generally received today | Potential tax benefit later |
| Taxes on qualified retirement withdrawals | Generally taxable | Generally tax-free |
| Investment growth | Tax-deferred | Qualified withdrawals can be tax-free |
| Employer availability | Depends on plan | Depends on plan |
| Best comparison factor | Current vs future tax rate | Current vs future tax rate |
The exact tax outcome depends on your circumstances and the applicable rules.
That is why entering realistic assumptions into a Roth or 401k calculator can be more useful than choosing an account based on a simple rule.
1. Compare Your Current Tax Rate With Your Expected Retirement Tax Rate
One of the biggest factors in a Roth versus traditional decision is your tax rate.
Suppose your current marginal tax rate is relatively high, but you expect your taxable income to be lower after retirement.
A traditional 401(k) could provide a tax benefit when you contribute because eligible pre-tax contributions generally reduce current federal taxable income.
On the other hand, someone who expects their tax rate to be higher later may place more value on paying taxes now through Roth contributions and potentially receiving qualified tax-free distributions later.
This is not a guarantee because future tax laws and personal circumstances can change.
John Hancock’s comparison calculator specifically explains that the choice can depend on whether you expect your tax rate to be higher now or during retirement.
Example
Imagine two hypothetical workers:
Worker A
- Current tax rate: relatively high
- Expected retirement tax rate: lower
- Long retirement timeline
Worker B
- Current tax rate: relatively low
- Expected retirement tax rate: higher
- Long retirement timeline
A traditional 401(k) may look more attractive under Worker A’s assumptions, while a Roth 401(k) may look more attractive under Worker B’s assumptions.
The calculator allows you to test these assumptions rather than relying on a generic answer.
2. Understand the Difference Between Pre-Tax and After-Tax Contributions
The phrase “tax advantage” can be confusing because both account types have tax advantages, but they work at different stages.
Traditional 401(k)
The tax benefit generally happens when you make the contribution.
For example, if part of your salary is contributed to a traditional 401(k), that eligible contribution generally isn’t included in your federal taxable income at the time of contribution.
The money can then grow within the retirement account, with taxes generally applying when taxable distributions are taken.
Roth 401(k)
The tax treatment is different.
Roth contributions are included in your taxable income when you make them. In return, qualified distributions from the Roth account can generally be received without federal income tax on the qualified amount.
This difference is one reason a Roth or 401k calculator can be useful.
You are not simply comparing two investment accounts.
You are comparing two different tax-timing strategies.
3. Include Your Employer Match
An employer match can be an important part of retirement planning.
Some employers contribute additional money when employees contribute to a 401(k). The amount and formula depend on the specific employer plan.
For example, an employer might offer a match based on a percentage of your salary and your contribution rate.
The IRS notes that employer matching contributions can be part of a 401(k) plan, although the specific rules and plan terms vary.
When using a Roth or 401k calculator, check how the calculator handles employer contributions.
This matters because your personal contribution and your employer’s contribution are not necessarily treated identically for tax purposes.
Your plan documents should explain exactly how your employer’s match works.
Why the match matters
Suppose your employer offers a matching contribution when you contribute to your workplace retirement plan.
If you contribute less than the amount needed to receive the full available match, you may be leaving part of that employer benefit unused.
The exact strategy depends on the plan.
So before focusing entirely on Roth versus traditional contributions, find out:
- Does your employer offer a match?
- What percentage is matched?
- Is there a maximum?
- Is there a vesting schedule?
- Does the match apply to Roth contributions?
- Where does the employer contribution go?
Your benefits department or plan documents can answer these questions.
4. Use the 2026 401(k) Contribution Limit
Contribution limits are another important part of retirement planning.
For 2026, the IRS says the employee elective deferral limit for most 401(k) plans is $24,500. Participants age 50 or older may generally make an additional $8,000 catch-up contribution, if the plan permits it. For employees who are age 60, 61, 62, or 63, the higher catch-up limit is $11,250 for 2026.
These limits matter when using a retirement calculator because your planned annual contribution should not automatically exceed the applicable legal limit.
For example, if you enter a very high annual contribution into a calculator without checking the current IRS rules, the result may not represent what you can actually contribute under your plan.
The IRS also explains that the limits generally apply across eligible plans, meaning you need to consider contributions to multiple applicable plans when determining whether you’ve exceeded the annual employee deferral limit.
Official source: IRS 2026 401(k) contribution limits
For Rank Math: Keep this external link as a normal followed link. Do not add rel="nofollow" to it.
5. Enter a Realistic Investment Return
A retirement calculator needs an assumed investment return because the account’s future value depends partly on investment performance.
But this is one area where you should be careful.
A calculator can show what happens if an investment earns a particular annual return, but it cannot tell you what the market will actually return in the future.
Mutual of America states that its retirement calculator uses an assumed annual rate of return and notes that actual investment returns depend heavily on the investments selected. It also warns that future returns cannot be predicted with certainty and that higher potential returns generally involve greater risk and volatility.
This is important because a small change in an assumed return can create a large difference in a long-term projection.
For example, a calculator might show different outcomes at:
- 4% annual return
- 6% annual return
- 8% annual return
Those numbers are hypothetical scenarios, not promises.
A better approach is to test multiple scenarios instead of relying on one optimistic estimate.
6. Consider Whether You Will Invest Traditional 401(k) Tax Savings
This is a detail many people miss.
A traditional 401(k) may reduce your current taxable income, which can create a tax benefit today.
But if you compare a traditional 401(k) with a Roth 401(k), you need to consider what happens to that tax savings.
For example, imagine a hypothetical $1,000 contribution.
If the traditional contribution creates a tax saving, you have an additional amount of money that could potentially be saved or invested.
If you spend that tax saving, the comparison is different from a scenario where you invest it.
Mutual of America’s Roth versus traditional calculator specifically includes an option to invest the tax savings generated by traditional contributions.
This is a valuable calculator setting because it creates a more balanced comparison.
The lesson is simple:
Don’t compare only the retirement account balances. Consider what happens to the tax savings outside the account as well.
7. Test Different Retirement Ages
Your retirement age can have a major effect on the projection.
If you contribute for a longer period, your account has more time to receive contributions and potentially benefit from investment growth.
If you retire earlier, you may have fewer contribution years and potentially a longer period during which retirement assets need to support you.
For this reason, a Roth or 401k calculator should ideally let you change your expected retirement age.
Try several scenarios:
Scenario A: Retire at 60
You may have fewer contribution years and potentially need your savings to support a longer retirement.
Scenario B: Retire at 65
This provides a longer accumulation period.
Scenario C: Retire at 70
You may have additional years for contributions and potential investment growth, although working longer is not the right choice for everyone.
These examples are simply planning scenarios.
The goal is to see how changing one assumption can affect the projected outcome.
Roth 401(k) vs Traditional 401(k): Which One Should You Choose?
There is no universal answer that works for every worker.
The better choice depends on factors such as:
- Current tax rate
- Expected retirement tax rate
- Income
- Retirement age
- Contribution amount
- Employer match
- Other retirement accounts
- Future income
- Investment strategy
- Personal financial goals
A Roth 401(k) may appeal to someone who wants to pay taxes on contributions today and potentially receive qualified distributions tax-free later.
A traditional 401(k) may appeal to someone who values the current tax deduction and expects to pay a lower tax rate in retirement.
Some workers may also have access to both options through their employer plan.
The IRS confirms that plans can permit employees to designate some or all elective deferrals as Roth contributions rather than traditional pre-tax contributions.
Instead of asking, “Which account is always better?” ask:
“Which tax treatment fits my current situation and my expectations for retirement?”
That is a much more useful question.
Can You Have Both a Roth and Traditional 401(k)?
Yes, if your employer’s plan allows both contribution types, you may be able to divide your employee contributions between traditional pre-tax and designated Roth contributions, subject to the applicable annual limits.
The IRS explains that a plan that permits designated Roth contributions can allow employees to designate some or all of their elective deferrals as Roth contributions.
This can give you some tax diversification.
For example, a hypothetical worker might contribute part of their retirement savings through a traditional 401(k) and another part through a Roth 401(k).
That does not automatically make the strategy better.
It simply means the person’s retirement money may have different tax treatments.
A Roth or 401k calculator can be useful here because you can compare different contribution mixes.
What Information Should You Enter Into a Roth or 401k Calculator?
For a more useful estimate, gather the following information first.
1. Current age
This determines how many years remain before your planned retirement.
2. Current 401(k) balance
Use your actual account balance rather than a rough estimate.
3. Annual salary
Your workplace retirement contributions and employer match may be tied to compensation.
4. Contribution percentage
Enter the percentage you currently contribute or the amount you plan to contribute.
5. Employer match
Check your employer’s actual matching formula.
6. Expected retirement age
This determines the estimated accumulation period.
7. Expected investment return
Use a reasonable planning assumption and test multiple scenarios.
8. Current tax rate
This helps compare the tax treatment of traditional and Roth contributions.
9. Expected retirement tax rate
This is particularly important when comparing the tax timing of traditional and Roth accounts.
10. Additional investment of tax savings
If the calculator provides this option, consider whether traditional 401(k) tax savings would actually be invested.
The more realistic your inputs, the more useful the comparison becomes.
A Simple Roth vs 401(k) Example
Consider a hypothetical 35-year-old worker.
Suppose they have:
- $50,000 already in a retirement account
- $80,000 annual salary
- 30 years until retirement
- Regular annual contributions
- An employer match
- A hypothetical investment return assumption
- A current tax rate that differs from their expected retirement tax rate
Instead of immediately deciding between Roth and traditional, they could run several scenarios.
Scenario 1: Traditional 401(k)
The worker makes pre-tax contributions and receives the current tax treatment associated with those contributions.
Scenario 2: Roth 401(k)
The worker makes after-tax Roth contributions and potentially receives tax-free treatment on qualified distributions.
Scenario 3: Traditional 401(k) plus invested tax savings
The worker contributes to the traditional account and invests the tax savings instead of spending them.
The third scenario is important because it changes the amount of money being invested outside the retirement account.
This example demonstrates why calculators can be useful.
They allow you to change one assumption at a time and see how the estimated outcome changes.
What a Retirement Calculator Cannot Tell You
A Roth or 401k calculator is useful, but it has limits.
It cannot predict:
- Future stock-market returns
- Future tax laws
- Your exact retirement expenses
- Your future salary
- Future inflation
- Unexpected career changes
- Future employer policies
- Your actual retirement date
- Changes in contribution limits
It also cannot tell you whether you will be happy with a particular investment strategy.
A calculator produces an estimate based on assumptions.
Mutual of America explicitly describes its calculator results as hypothetical and says its tools are intended for self-help rather than personalized investment advice.
That is an important distinction.
Use the calculator to understand possibilities, not to treat the final number as a promise.
How to Use a Roth or 401k Calculator Step by Step
Here is a simple process you can follow.
Step 1: Find your current retirement balance
Log into your workplace retirement account and use the actual number.
Step 2: Check your contribution rate
Look at your current payroll contribution.
Step 3: Review your employer match
Read your plan documents to understand the exact matching formula.
Step 4: Check the current IRS contribution limit
For 2026, the regular employee 401(k) elective deferral limit is $24,500, subject to the applicable rules.
Step 5: Enter your current tax assumptions
Do not simply guess if you can verify your marginal tax rate from your tax information.
Step 6: Estimate your retirement tax rate
This is uncertain, so consider testing more than one scenario.
Step 7: Run the traditional 401(k) scenario
Record the estimated result.
Step 8: Run the Roth 401(k) scenario
Use comparable assumptions.
Step 9: Test a mixed strategy
If your plan allows it, compare a combination of traditional and Roth contributions.
Step 10: Review the assumptions
Do not focus only on the final dollar amount.
Look at what assumptions produced that result.
Roth 401(k) vs Traditional 401(k) Comparison Table
| Factor | Traditional 401(k) | Roth 401(k) |
|---|---|---|
| Contributions | Generally pre-tax | After-tax |
| Taxes paid on contribution | Generally later | Generally now |
| Current taxable income | Generally reduced by eligible contribution | Contribution included in taxable income |
| Qualified retirement withdrawals | Generally taxable | Generally tax-free |
| Useful consideration | Current tax savings | Future tax-free qualified distributions |
| Calculator inputs | Tax rate, contribution, return, retirement age | Same |
| Employer match | Depends on plan | Depends on plan |
| Main question | Is a current tax benefit valuable? | Is paying tax now attractive? |
The IRS confirms the different tax treatment of traditional and designated Roth contributions and distributions.
Common Mistakes When Using a Roth or 401k Calculator
Using an unrealistic investment return
A very high assumed return can make the final number look impressive but may not be a sensible planning assumption.
Test multiple scenarios instead.
Ignoring taxes
The biggest difference between traditional and Roth accounts is tax timing.
If you ignore taxes, you are not making a meaningful comparison.
Forgetting employer contributions
Your employer match can affect the overall retirement projection.
Treating the calculator result as guaranteed
The number is an estimate, not a promise.
Ignoring inflation
A future retirement balance may look large in nominal dollars but have less purchasing power than the same amount today.
Spending traditional-account tax savings
If your comparison assumes that you invest your traditional 401(k) tax savings but you actually spend that money, your real-world result will differ from the calculator.
Assuming Roth is always better
Roth contributions can be valuable, but the right choice depends on tax rates, income, retirement plans, and personal circumstances.
How This Connects to Long-Term Investing
Retirement planning and investing are closely connected.
A 401(k) is an account structure, not a single investment.
Inside a 401(k), your contributions are generally invested according to the options offered by your plan. Your actual investment choices determine how the account behaves over time.
The IRS describes defined-contribution retirement accounts as accounts where contributions and investment gains or losses affect the eventual account value, after applicable fees and other factors.
That means choosing Roth versus traditional is only one part of retirement planning.
You should also understand:
- What your plan invests in
- Investment fees
- Diversification
- Risk
- Time horizon
- Contribution rate
- Employer match
- Retirement income needs
This is why the best use of a Roth or 401k calculator is not simply to find a winning account.
It is to understand how several decisions work together.
When Should You Revisit Your Roth vs Traditional Decision?
Your circumstances can change.
You may want to review your retirement strategy after:
- A significant salary increase
- A career change
- Marriage
- Divorce
- Starting a business
- A major change in tax situation
- Receiving a large promotion
- Moving to another state
- Approaching retirement
- Changes to your employer’s retirement plan
A decision that made sense earlier in your career may not fit your situation later.
For example, someone early in their career may have a different tax situation from someone earning significantly more later.
That is why retirement planning should be treated as an ongoing process rather than a one-time decision.
Internal Links for WealthNivo
You can add these 3 internal links naturally inside the article:
Internal Link 1
Add this sentence in the section “How This Connects to Long-Term Investing”:
Before increasing your retirement contributions, it can also help to understand how much should be in savings so your emergency fund and long-term investments have separate jobs.
Internal Link 2
Add this sentence after the section “Can You Have Both a Roth and Traditional 401(k)?”:
If you are building your retirement plan in your 30s, our guide on how much you should have saved for retirement at 35 can give you another benchmark to consider.
How Much Should You Have Saved for Retirement at 35?
Internal Link 3
Add this sentence near the beginning of the article after explaining budgeting and retirement contributions:
A strong retirement strategy starts with good cash-flow management, so learning what a budget can help you do is a useful next step.
What Can a Budget Help You Do?
Final Thoughts on the Roth or 401k Calculator
A Roth or 401k calculator can make retirement planning easier because it turns an abstract tax decision into a side-by-side comparison.
The traditional 401(k) generally provides its tax benefit when eligible contributions are made, while Roth 401(k) contributions are taxed upfront and can receive tax-free treatment when distributions are qualified.
Neither option is automatically right for everyone.
Your current tax rate, expected retirement tax rate, contribution amount, employer match, investment assumptions, retirement age, and broader financial situation all matter.
For 2026, the IRS sets the regular employee 401(k) elective deferral limit at $24,500, with additional catch-up provisions for eligible older workers.
The smartest way to use a calculator is to run several reasonable scenarios rather than chasing one perfect answer.
Start with your real numbers. Compare traditional and Roth contributions. Include employer contributions where appropriate. Test different tax rates and investment-return assumptions. Then review the result alongside your emergency savings, debt, other investments, and retirement goals.
A calculator cannot predict your financial future.
But it can help you understand the choices that shape it.