Brokerage Account vs Mutual Fund: 9 Powerful Key Differences
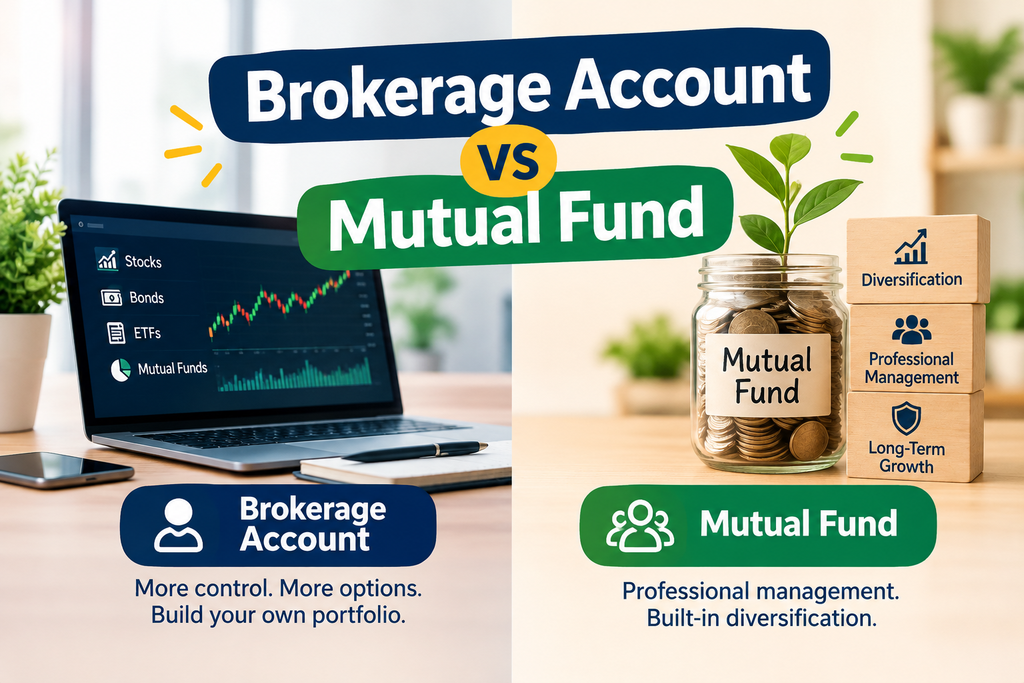
If you are comparing brokerage account vs mutual fund, the first thing to know is that they are not actually the same type of financial product. A brokerage account is an investment account used to buy, sell, and hold investments, while a mutual fund is an investment product that pools money from many investors and invests it in a portfolio.
That distinction matters because you can use a brokerage account to buy mutual funds. A brokerage account can also give you access to stocks, bonds, ETFs, and other investments, depending on the brokerage firm. The U.S. Securities and Exchange Commission’s Investor.gov explains that brokerage accounts can be used to buy and sell a variety of investment products, including stocks, bonds, mutual funds, and ETFs.
For beginners, this can make investing terminology confusing. Someone may say they “invest through a brokerage account,” while another person says they “invest in mutual funds.” Both can be correct.
The better question is not simply whether you should choose a brokerage account or a mutual fund. Instead, you should understand what each one does, how they can work together, what they cost, how much control they provide, and what risks are involved.
This guide explains the difference between a brokerage account and a mutual fund in simple terms and shows how each can fit into a long-term investment strategy.
Brokerage Account vs Mutual Fund: Quick Comparison
| Feature | Brokerage Account | Mutual Fund |
|---|---|---|
| What is it? | An investment account | An investment product |
| Main purpose | Holds and provides access to investments | Pools investors’ money into a portfolio |
| Stocks | Can generally hold stocks | Some mutual funds invest in stocks |
| Bonds | Can generally hold bonds | Some mutual funds invest in bonds |
| ETFs | Can generally hold ETFs | Not an ETF itself |
| Mutual funds | Can hold mutual funds | It is itself a mutual fund |
| Investment control | Investor chooses available investments | Fund follows its stated investment strategy |
| Diversification | Depends on what you buy | Often provides diversification, depending on holdings |
| Professional management | Not automatically included | Generally managed by an investment adviser |
| Trading | Depends on the investment | Generally purchased or redeemed based on NAV |
| Fees | Depend on brokerage and investments | Fund expenses and possible additional charges |
| Can they be combined? | Yes | Yes |
The simplest way to remember the difference is:
A brokerage account is where you hold investments.
A mutual fund is an investment you can hold.
That means they are not necessarily competing choices.
What Is a Brokerage Account?
A brokerage account is an investment account opened with a brokerage firm. It allows investors to buy and sell investment products such as stocks, bonds, mutual funds, and ETFs.
Think of a brokerage account as a container.
The account gives you access to investments, but the account itself does not determine what your portfolio looks like.
For example, an investor could have a brokerage account containing:
- Individual stocks
- Bonds
- ETFs
- Mutual funds
- Other eligible investments
- Uninvested cash
The exact choices depend on the brokerage firm and account.
This is important because simply opening a brokerage account does not automatically create a diversified portfolio. Your portfolio depends on what you actually purchase.
One investor might use a brokerage account to buy a handful of individual stocks. Another might use the same type of account to buy diversified mutual funds or ETFs.
The account provides the structure. The investments determine the portfolio.
Cash Brokerage Accounts
A cash account is a type of brokerage account where the investor generally pays the full amount for securities purchased. You do not borrow money from the brokerage firm to make the purchase.
For many beginners, a cash account can be easier to understand because it avoids the additional risks associated with borrowing.
Margin Brokerage Accounts
A margin account allows a brokerage firm to lend money to the investor for purchasing securities, using eligible investments as collateral. Margin introduces borrowing costs and additional risk.
If investments purchased with borrowed money decline, the investor can face additional losses and may have to provide more cash or securities to the account. In certain situations, the brokerage firm may sell securities to cover a shortfall.
For beginners, it is important to understand how margin works before using it.
What Is a Mutual Fund?
A mutual fund is an investment product that pools money from many investors and invests that money in securities or other assets according to the fund’s strategy.
A mutual fund may invest in:
- Stocks
- Bonds
- Short-term money-market instruments
- Other securities
- A combination of assets
The fund’s holdings make up its portfolio. The portfolio is managed by an investment adviser according to the fund’s stated objective and strategy.
Instead of choosing every individual investment yourself, you purchase shares of the mutual fund.
For example, suppose a mutual fund owns shares of many different companies. Rather than buying every company separately, an investor can buy shares of the fund and gain exposure to the fund’s portfolio.
This is one reason mutual funds are widely used by investors who want diversification or professional management.
However, not every mutual fund has the same level of diversification.
A fund may focus on a particular industry, country, asset class, or investment strategy. So investors should look at the actual holdings and objective rather than assuming every mutual fund is broadly diversified.
Brokerage Account vs Mutual Fund: What Is the Main Difference?
The main difference is simple:
A brokerage account is an account, while a mutual fund is an investment product.
This distinction is the foundation for understanding the entire topic.
Imagine you open a brokerage account.
You might then use that account to purchase:
- A mutual fund
- An ETF
- Individual stocks
- Bonds
- Other available securities
The brokerage account gives you access to the investments.
The mutual fund is one of those investments.
This is why asking whether a brokerage account is “better” than a mutual fund can be misleading. They perform different functions.
A more useful comparison is whether you want to manage investments yourself or use a pooled investment such as a mutual fund for part of your portfolio.
9 Key Differences Between a Brokerage Account and Mutual Fund
1. Level of Investment Control
The first major difference is control.
A brokerage account can give investors substantial flexibility because they can choose from the investments available through the brokerage.
If you want to research individual companies and purchase their stocks, a brokerage account may provide the structure to do that.
You could also choose ETFs, bonds, or mutual funds instead.
With a mutual fund, the fund’s investment adviser generally decides which securities to buy and sell according to the fund’s strategy.
That means you are not normally selecting every individual security inside the fund.
This can be useful for investors who prefer a professionally managed portfolio.
The trade-off is less direct control over individual holdings.
Simple example
A self-directed investor might say:
“I want to choose the companies in my portfolio.”
A mutual fund investor might say:
“I want exposure to a portfolio without selecting every company myself.”
Neither approach is automatically suitable for everyone. The choice depends on your goals, knowledge, time, and willingness to manage investments.
2. Diversification
Diversification is another major difference to consider.
A brokerage account does not automatically diversify your money.
If you use a brokerage account to purchase one company’s stock, your portfolio could be highly concentrated.
If you use the same brokerage account to purchase several diversified funds, your portfolio could have exposure to a much larger number of securities.
Mutual funds can make diversification easier because one fund may hold many different investments. Investor.gov identifies diversification as one of the features that can make mutual funds useful to investors.
But there is an important limitation.
A mutual fund can still be concentrated.
For example, a fund focused on one sector may have substantial exposure to companies in that sector. A fund focused on one country may also be exposed to country-specific economic and political risks.
Before investing, review the fund’s holdings and strategy.
Do not judge diversification simply from the words “mutual fund.”
3. Professional Management
Professional management is another key difference.
Mutual funds are generally managed by investment advisers according to their stated investment objectives.
This means the fund manager or investment team makes decisions about the portfolio within the fund’s strategy.
A standard brokerage account does not automatically include professional portfolio management.
If you purchase individual stocks through a brokerage account, you may be responsible for:
- Researching companies
- Choosing investments
- Deciding when to buy
- Deciding when to sell
- Monitoring your portfolio
- Rebalancing when appropriate
Some brokerage firms also provide investment advisory services, but a brokerage account and an advisory account are not necessarily the same thing. Investor.gov notes that different investment accounts can have different services, fee structures, and tax treatment.
So, when comparing the two, ask whether you want to make investment decisions yourself or use a professionally managed pooled investment.
4. Fees and Expenses
Costs are another important part of the brokerage account vs mutual fund comparison.
Brokerage accounts may have different fees depending on the firm and services provided.
Potential costs can include:
- Account fees
- Transfer fees
- Wire fees
- Margin interest
- Investment-related fees
- Other service charges
Investor.gov explains that brokerage firms may charge different types of account fees and that investors should review the firm’s fee information before opening an account.
Mutual funds have their own expenses.
These can include fund operating expenses and investment management costs. Some mutual funds can also have sales charges or other applicable fees.
The important point is that the cost of investing is not determined only by whether you use a brokerage account.
You need to look at both:
Account costs + investment costs
A low-cost brokerage account can still hold an expensive mutual fund.
Likewise, a brokerage account holding a low-cost investment may have a different overall cost structure.
Always check the actual fees before investing.
5. How Investments Are Bought and Sold
Stocks, ETFs, and mutual funds do not all trade in exactly the same way.
Mutual funds generally allow investors to buy shares from the fund or through a broker or investment adviser. Mutual fund purchases and redemptions are generally based on the fund’s next calculated net asset value, or NAV. NAV is typically calculated at the end of each business day.
Stocks and ETFs work differently.
Retail investors generally buy and sell stocks and ETFs through market transactions while the relevant market is open.
This distinction can matter if you care about intraday trading.
For a long-term investor, however, the more important issues may be the investment strategy, diversification, costs, risk, and time horizon.
6. Risk
Neither a brokerage account nor a mutual fund is automatically safe.
The risk comes primarily from the investments you own and how the portfolio is structured.
For example, a brokerage account holding one volatile stock may have significant concentration risk.
A brokerage account holding diversified funds could spread exposure across many securities.
A mutual fund can also lose value.
Investor.gov explains that mutual funds are not insured by the FDIC or another government agency and that investors can lose some or all of their money.
Diversification can reduce the impact of one investment performing poorly, but it cannot eliminate market risk.
This is an important lesson for beginners:
Diversification can spread risk, but it cannot guarantee a profit.
Investment values can rise and fall.
7. Taxes
Taxes are another area where investors should be careful.
A taxable brokerage account may create taxable events when investments are sold for a gain.
Mutual funds held in taxable accounts can also distribute income or capital gains to investors.
The exact tax result depends on several factors, including:
- Account type
- Investment type
- Purchase price
- Sale price
- Holding period
- Distributions
- Local tax laws
This means you should not assume that “brokerage account” automatically means one tax result or that “mutual fund” automatically means another.
Tax-advantaged investment accounts can have different rules from ordinary taxable brokerage accounts.
Because tax laws vary by country and individual circumstances, investors should check the rules that apply to their situation or consult a qualified tax professional.
8. Flexibility
Flexibility is one of the main advantages of a brokerage account.
Depending on the brokerage firm, you may be able to hold different types of investments within one account.
For example:
Brokerage account
→ Stocks
→ Bonds
→ ETFs
→ Mutual funds
→ Other eligible investments
A mutual fund is more specific.
When you buy a mutual fund, you are purchasing an investment with a defined strategy.
That can make investing easier because you do not need to select every individual security yourself.
However, you are also accepting the fund’s investment approach.
If the fund focuses on a particular sector or asset class, your portfolio will reflect that strategy.
9. Minimum Investments and Accessibility
Minimum investment requirements vary.
Some mutual funds may have minimum initial investments, while others may have relatively low minimums.
Brokerage firms may also have account-opening requirements, investment minimums, or restrictions depending on the products available.
Before opening an account or purchasing a fund, check the current requirements.
This can be particularly important for beginners who are starting with a small amount of money.
Other features can matter too, including:
- Fractional-share availability
- Automatic investing
- Recurring contributions
- Account fees
- Investment selection
- Mobile access
- Research tools
The easiest platform to use is not necessarily the cheapest, and the cheapest platform is not automatically the best fit.
Look at the complete cost and feature set.
Can You Buy a Mutual Fund Through a Brokerage Account?
Yes, you can buy mutual funds through a brokerage account.
This is one of the most important points to understand when researching brokerage account vs mutual fund.
Investor.gov states that brokerage accounts can be used to buy and sell investment products including mutual funds.
Think about it this way:
Brokerage account = account
Mutual fund = investment
For example:
You → Brokerage Account → Mutual Fund
You open the account, deposit money, and then purchase an eligible mutual fund.
You could potentially use the same brokerage account to buy other investments as well.
This is why the two can work together.
Brokerage Account vs Mutual Fund for Beginners
For beginners, the most important step is to separate the account decision from the investment decision.
If you want to select individual stocks, ETFs, bonds, and funds yourself, a brokerage account may give you the flexibility to do that.
If you want a pooled portfolio managed according to a defined strategy, a mutual fund may be one option to consider.
But a beginner does not necessarily need to choose between the two.
You can open a brokerage account and use it to purchase mutual funds.
Before investing, think about:
- Your financial goal
- Your time horizon
- Your risk tolerance
- Your emergency savings
- Your existing debt
- Your investment knowledge
- Investment fees
- Diversification
- Taxes
- Liquidity
If you are still working on the basics, start with our Personal Finance Tips for Beginners to build a stronger foundation around budgeting, saving, debt management, and investing.
A strong investment strategy usually starts with strong money-management habits.
Savings vs Investing: Why the Difference Matters
Investing is only one part of a complete financial plan.
Before putting money into investments, consider how much cash you need for emergencies and near-term expenses.
An emergency fund has a different purpose from a long-term investment portfolio.
Savings can provide accessible money for unexpected expenses.
Investments are generally intended for longer-term goals and can fluctuate in value.
If you are still deciding how much cash to keep available, read our guide on How Much Should Be in Savings for a practical framework based on expenses, income stability, and financial responsibilities.
The key idea is simple:
Short-term needs → accessible savings
Long-term goals → investments
Keeping those purposes separate can help you avoid selling investments at an inconvenient time because of an unexpected expense.
How Budgeting Can Help You Invest More
A brokerage account or mutual fund can only become part of your investment strategy if you have money available to invest.
That is where budgeting matters.
A realistic budget can show you how much money comes in, how much goes toward essential expenses, and how much remains for savings and long-term goals.
Our guide, What Can a Budget Help You Do?, explains how budgeting can create room for savings, debt repayment, and investing.
You do not need a perfect budget.
You need a system you can follow.
For example, after receiving your income, you might divide it among:
- Essential expenses
- Debt payments
- Emergency savings
- Long-term investments
- Lifestyle spending
The exact percentages depend on your circumstances.
The important thing is to give your money a purpose.
How to Evaluate a Mutual Fund Before Investing
If you decide to consider mutual funds, do not choose one simply because someone calls it the “best fund.”
Instead, review the actual investment.
Investment Objective
Find out what the fund is designed to accomplish.
Does it focus on growth, income, capital preservation, a specific sector, or another strategy?
Portfolio Holdings
Look at what the fund actually owns.
The fund’s name alone may not tell you how concentrated or diversified it is.
Fees
Review the expense ratio and other applicable charges.
Higher costs can reduce the amount of your investment return that remains with you.
Risk
Understand how the fund can lose value.
A stock-focused fund will generally have different risks from a fund focused on short-term debt instruments.
Management Strategy
Understand whether the fund is actively managed, follows an index, or uses another approach.
Minimum Investment
Check whether the fund requires a minimum initial investment or ongoing contribution.
Prospectus
Read the fund’s prospectus and available shareholder information before investing.
Investor.gov provides information about mutual funds, their structure, management, diversification, and purchasing process.
Common Mistakes to Avoid
Mistake 1: Thinking a Brokerage Account Is an Investment
A brokerage account is the account structure.
The investment is what you purchase inside it.
Opening an account does not automatically create a diversified portfolio.
Mistake 2: Assuming Every Mutual Fund Is Diversified
Many mutual funds hold multiple securities, but some are narrowly focused.
Review the holdings.
Mistake 3: Ignoring Fees
Small costs can matter over long periods.
Look at both account costs and investment costs.
Mistake 4: Using Margin Without Understanding It
Margin involves borrowing money and can increase losses as well as purchasing power.
Mistake 5: Investing Emergency Savings
Investments can lose value.
Money you may need for an emergency should be considered separately from money intended for long-term investing.
Mistake 6: Choosing a Fund Only Because of Past Returns
Strong historical performance does not guarantee future results.
Consider the fund’s strategy, risk, fees, holdings, and suitability for your goals.
Mistake 7: Treating All Mutual Funds as the Same
Equity funds, bond funds, money-market funds, balanced funds, and other fund types can have very different objectives and risks.
Always look at the specific fund.
Brokerage Account vs Mutual Fund: Which Is More Flexible?
A brokerage account is generally more flexible in terms of the range of investments you can potentially hold.
Depending on the provider, you may be able to combine stocks, bonds, ETFs, mutual funds, and other eligible investments in one account.
A mutual fund is more structured.
You choose the fund, but the fund’s investment team manages the underlying portfolio according to its strategy.
For someone who wants to select individual securities, the brokerage-account structure can provide greater direct control.
For someone who prefers a pooled portfolio, a mutual fund may provide a simpler way to gain exposure to a group of investments.
Again, these are not mutually exclusive.
A brokerage account can hold mutual funds.
Brokerage Account vs Mutual Fund for Long-Term Wealth Building
The investing role of these two tools becomes clearer when you think about long-term wealth building.
A brokerage account can provide the platform you use to hold investments.
A mutual fund can provide a diversified or specialized portfolio within that account.
Neither guarantees wealth.
Long-term results can depend on:
- How much you invest
- How consistently you invest
- What you invest in
- Investment fees
- Taxes
- Time horizon
- Market performance
- Risk management
- Portfolio diversification
That is why building wealth is usually about creating a sustainable financial system rather than finding one perfect investment.
A budget can help you identify money available for investing.
Savings can provide a financial cushion.
Debt management can reduce financial pressure.
Investing can give appropriate long-term money an opportunity to grow.
Each part serves a different purpose.
A Simple Example of How They Can Work Together
Imagine an investor decides to invest $500 per month for a long-term financial goal.
The investor opens a brokerage account.
Instead of buying individual stocks, the investor chooses a diversified mutual fund that fits their investment objective and risk tolerance.
The $500 monthly contribution is then used to purchase additional fund shares according to the fund’s transaction rules.
In this example:
Brokerage account: provides the account structure.
Mutual fund: provides the underlying investment portfolio.
Monthly contribution: provides ongoing investment capital.
Time: gives the investment strategy an opportunity to compound, although returns are never guaranteed.
This example shows why comparing the two as if they are direct substitutes can create confusion.
How to Decide What Fits Your Investment Approach
Ask yourself these questions before making a decision.
Do I want to select individual investments?
If yes, a brokerage account can give you the flexibility to make those choices.
Do I prefer a professionally managed portfolio?
If yes, mutual funds may be worth researching.
Do I want diversification?
Look at the actual portfolio rather than relying on the product name.
Do I want to keep costs low?
Compare both account fees and investment expenses.
Do I need access to several investment types?
A brokerage account can provide access to multiple products depending on the provider.
Am I investing for a long-term goal?
Your time horizon should influence how you think about risk and asset allocation.
Do I understand what I am buying?
If not, learn more before investing.
That final question is often the most important.
SEC Investor.gov Resource for Brokerage Accounts
For an authoritative explanation of brokerage accounts, investors can review the SEC’s Investor.gov brokerage account guide, which explains what brokerage accounts are, what they can hold, and the difference between cash and margin accounts.
Recommended outbound anchor text: SEC Investor.gov Brokerage Accounts
This is a useful external resource because it comes directly from the U.S. Securities and Exchange Commission’s investor-education website.